Problem Solving the Philippines: A Primer on the National Budget
By Giancarlo Angulo
Preface
For some time the company I worked for maintained eBudget, URS, OSBP, and most of the budget-related systems. That ended when I resigned to start consulting for the SEC. As I often try to do, I do not like not knowing the main processes, the main workflow, the main decision points, and the main things the IT system does. In the end, IT is just a means to an end. The IT system serves the business goals.
This primer is a way to demystify the budget and to add to what is in the public domain. During the time of Secretary Abad, the guiding principle was Budget ng Bayan: bridging the budget so people could understand how it serves their needs. Open Data was a big buzzword then. During GMA’s time I remember the PFM work that probably guided a lot of the reforms in public financial management. Those topics are for another time.
I must confess that this post was inspired by the recent Supreme Court ruling. That ruling is the subject of part 4.
This is part 1 of 4 in The Budget Series. This part is the overview: who does what, the budget year, the rules on Congress, and where the money goes. Part 2 covers how the National Expenditure Program is generated. Part 3 covers how the budget is managed once it is signed. Part 4 covers how the rules have been tested, including the Supreme Court ruling.
The question
Where does a peso in the national budget come from, and who can change it at each step?
TLDR
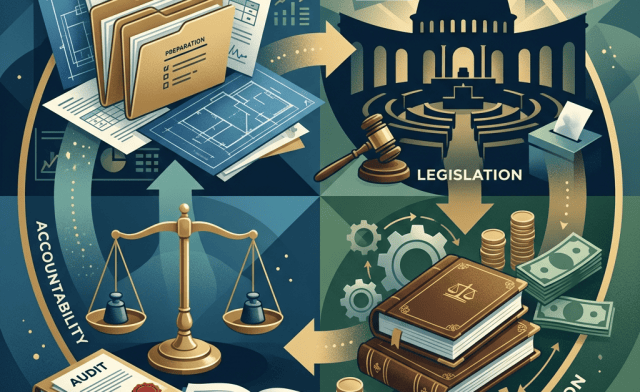
- The budget runs in four phases: preparation, legislation, execution and accountability. The executive runs the first and the third, Congress the second, and the Commission on Audit (COA) the fourth.
- Congress can cut the President’s proposed budget but cannot raise it (Constitution, Article VI, Section 25(1)).
- A peso that is appropriated is not a peso that is spent. On June 30, 2026, agencies had obligated 49.5% of the allotments released to them.
- The previous year’s budget has been re-enacted, in whole or in part, in 12 fiscal years since 2001, including a full year in 2001, 2004 and 2006.
- This post is accurate as of October 24, 2026.
Who does what
| Step | Who | What they decide | The limit |
|---|---|---|---|
| Set the numbers | Development Budget Coordination Committee (DBCC), chaired by the DBM Secretary, with DEPDev, the DOF, the Office of the President and the BSP (as the Supreme Court describes it) | Growth, inflation and revenue assumptions; the total budget and deficit | Must be consistent with the medium-term fiscal program |
| Call for proposals | Department of Budget and Management (DBM) | What agencies may ask for, and when | The budget call and later memos |
| Propose | Each agency | Tier 1 (ongoing) and Tier 2 (new or expanded) requests | Ceilings set by DBM |
| Submit | The President | The National Expenditure Program (NEP) | Within 30 days of Congress opening its session (Art. VII, Sec. 22) |
| Start the bill | House of Representatives | Appropriation bills begin here | Art. VI, Sec. 24 |
| Amend | Senate, then a bicameral conference committee | Reconcile the two versions | Only real differences between the two versions (see part 4) |
| Sign or veto | The President | Approve, or veto particular items | Cannot add items; override needs two-thirds of each House |
| Release | DBM | Allotments and cash | The budget law’s own rules |
| Spend | Agencies | Obligate and pay | Validity period, then reversion |
| Audit | COA | Post-audit of the accounts | Art. IX-D, Sec. 2 |
The budget year, using FY2027 as the example
1. Preparation (executive). The cycle for fiscal year 2027 opened on January 5, 2026, when DBM issued National Budget Memorandum No. 156, the budget call. It aligns the budget with the Philippine Development Plan midterm update and applies the Cash Budgeting System: only programs that are ready to be implemented and can be completed within the year, or within the allowed implementation period, are meant to be funded. Regional priority projects need endorsement from the Regional Development Councils.
Agencies file in two tiers. Tier 1 is the cost of ongoing programs at the same cost and quality. Tier 2 is new or expanded spending, ranked against a Budget Priorities Framework (NBM 157, March 16; Tier 2 proposals due April 24). Proposals go in through DBM’s Online Submission of Budget Proposals system. The DBCC approved the macroeconomic assumptions on May 25 and the fiscal program on June 16. Executive Review Board hearings ran June 1 to 15, and NBM 158 (June 25) gave each agency its FY2027 ceiling. After a presentation to the President and Cabinet, DBM handed the NEP to the President on August 10 and to the House on August 11. Part 2 goes through how the NEP is built.
2. Legislation (Congress). The Constitution gives the President 30 days from the opening of the regular session to submit the budget. Congress opened on the fourth Monday of July, which was July 27, so the deadline would have been August 26 (my arithmetic). The House acts first. The Senate amends. If the two versions differ, a bicameral conference committee reconciles them. The President then signs, or vetoes particular items.
There is also a safety net. If Congress has not passed the new budget by year end, the previous year’s budget is deemed re-enacted (Art. VI, Sec. 25(7)). Justice Singh, in a separate opinion in the October 2026 ruling, traces the rule to Section 7 of the 1902 Philippine Organic Act, which kept the colonial government running if the Philippine Assembly failed to pass appropriations. It has been used more often than most of us remember:
| Fiscal year | Budget that was re-enacted | How long | Source |
|---|---|---|---|
| 2001 | 2000 budget | Full year | DBM; Abad |
| 2002 | 2001 budget | Until January 21, 2002 | Abad |
| 2003 | 2002 budget | Until May 12, 2003 (Abad); “3 months” (DBM) | Abad; DBM |
| 2004 | 2003 budget | Full year | DBM; Abad |
| 2005 | 2003 budget, as re-enacted | Until March 16, 2005 (Abad); “4 months” (DBM) | Abad; DBM |
| 2006 | 2005 budget | Full year | DBM; Abad |
| 2007 | 2005 budget, as re-enacted | Until March 23, 2007 | Abad |
| 2008 | 2007 budget | Until March 16, 2008 (Abad); “3 months” (DBM) | Abad; DBM |
| 2009 | 2008 budget | Until March 16, 2009 (Abad); “3 months” (DBM) | Abad; DBM |
| 2010 | 2009 budget (RA 9524) | Until the 2010 budget (RA 9970, approved February 8, 2010) | DBM circulars 2010-1 and 2010-2 |
| 2019 | 2018 budget (RA 10964) | The 2019 budget (RA 11260) was signed April 15, 2019; DBM charged releases to the re-enacted budget from January 2 to April 30 | Rappler; DBM |
| 2026 | 2025 budget (RA 12116) | Until January 4, 2026; the 2026 budget (RA 12314) took effect January 5 | DBM Circular 599 |
I found no re-enacted budget between 2011 and 2018 or between 2020 and 2025. I did not look at years before 2001. Where two sources give different lengths for the same year, I show both. DBM’s own 2019 briefing listed only 2001, 2004 and 2006 as full years and 2003, 2005, 2008 and 2009 as partial years. Former Budget Secretary Florencio Abad wrote in 2014 that all budgets from 2001 to 2010 were re-enacted at least in part, and the DBM circulars show that 2010 was one of them. The 2019 briefing said the 2019 budget was the first re-enacted one in eight years, and the dates above put the previous one in early 2010.
What a re-enacted budget means in practice: agencies can keep the lights on but not start much that is new. In the first quarter of 2019, DBM let agencies obligate up to 25% of the lower of the 2018 budget or the proposed 2019 amount for regular programs and ongoing foreign-assisted projects. Centrally managed items and special purpose funds needed a separate release on a special budget request. DBM listed the costs: the fourth tranche of the salary increase for about 1.4 million civilian personnel was delayed by a quarter (P10.72 billion), pension benefits were not indexed, and P28.4 billion of ongoing and P43.74 billion of new infrastructure projects were affected. In 2010 the January limit was one twelfth per month. Abad’s paper makes a further point: a re-enacted budget leaves the President more savings to use at their discretion, which tilts the balance toward the executive. The 2026 gap lasted four days, but in 2001, 2004 and 2006 the country ran a full year on the previous budget.
3. Execution (executive). The budget law is itself the “allotment order” for most items, meaning agencies may obligate under it. Items with conditions, or lump sums without details, need a Special Allotment Release Order (SARO) or General Allotment Release Order (GARO) from DBM. Cash comes separately through Notices of Cash Allocation (NCA), issued by quarter and “subject to actual agency disbursement performance”. Under the 2026 budget law (Section 77), appropriations are valid for release and obligation until December 31, 2027, except personnel services, which is December 31, 2026. After that, unreleased and unobligated amounts revert to the General Fund unless Congress acts again. Part 3 goes through how the budget is managed.
4. Accountability. COA audits after the fact. I have kept this part short because I have not researched it beyond the Constitution.
What Congress can and cannot do
The Constitution has more rules about the budget than most of us remember. The ones that matter for this post:
- Congress “may not increase the appropriations recommended by the President” (Art. VI, Sec. 25(1)). It can cut, and it can move money around within the total. The ceiling comes from the 1935 Constitution, was dropped in 1973, and was restored in 1987 after a member of the Constitutional Commission raised it (Justice Singh’s opinion).
- No provision may be placed in the general appropriations bill unless it relates specifically to a particular appropriation in it (Sec. 25(2)). This is the “rider” rule behind the PhilHealth ruling in December 2025.
- No law may authorize transfers of appropriations. Only the President, the Senate President, the Speaker, the Chief Justice and the heads of constitutional commissions may be authorized to augment items in their own offices from savings (Sec. 25(5)).
- The President may veto “any particular item or items” without affecting the rest (Sec. 27(2)). The President cannot rewrite them.
Three kinds of money in the proposal
The FY2027 proposal is P7,200.2 billion, up P407.0 billion, or 6.0%, from the 2026 budget of P6,793.2 billion. It is 21.7% of GDP. It has three kinds of money, shown here down to their main lines (amounts in billions of pesos):
| Kind | Component | Amount | Share of total |
|---|---|---|---|
| Programmed | 4,494.1 | 62.4% | |
| Departments and agencies | 3,858.2 | 53.6% | |
| Special purpose funds | 635.9 | 8.8% | |
| Automatic | 2,706.1 | 37.6% | |
| National Tax Allotment (to local governments) | 1,319.8 | 18.3% | |
| Interest payments | 1,114.3 | 15.5% | |
| BARMM block grant | 104.2 | 1.4% | |
| Retirement, life and insurance premiums | 89.0 | 1.2% | |
| Special accounts | 35.6 | 0.5% | |
| Net lending | 28.7 | 0.4% | |
| Tax expenditures | 14.5 | 0.2% | |
| Unprogrammed | 112.0 | 1.6% | |
| Restoring the fund balances of the PDIC | 57.0 | 0.8% | |
| Support to foreign-assisted projects | 42.6 | 0.6% | |
| Conversion of national government advances into subsidy for GOCCs | 8.8 | 0.1% | |
| Program on risk management | 3.6 | 0.05% | |
| Total | 7,200.2 | 100.0% |
Source: DBCC briefing to Congress, August 17, 2026 (slides 4 to 6). Shares are of the P7,200.2 billion total, so lines may not add exactly because of rounding. Two automatic lines, military camp sales proceeds and pensions of former presidents and widows, are zero at this precision.
- Programmed is the money with identified sources. The proposal rolls it up into two parts: what departments and agencies spend directly (P3,858.2 billion), and special purpose funds (P635.9 billion), which are lump-sum accounts managed centrally. The Court’s list for the 2024 budget included the Contingent Fund, the National Disaster Risk Reduction and Management Fund, the Pension and Gratuity Fund and budgetary support to government corporations. The deck I used does not break the P3,858.2 billion down by department on its own; its department table includes automatic appropriations.
- Automatic is spending that existing laws already require, led by the National Tax Allotment and interest payments, which together are more than a third of the whole proposal.
- Unprogrammed is standby authority: money that can be spent only if revenues come in above target or certain other funds arrive. The Supreme Court calls it a “narrow contingent appropriation”. The FY2027 proposal cuts it to P112.0 billion, from P249.9 billion proposed for 2026.
By sector, the proposal puts social services at 34.1%, economic services at 25.5%, general public services at 18.3%, debt burden at 15.9% and defense at 6.3%. By recipient, national agencies get 60.2%, local governments 21.3%, interest 15.5% and government corporations 3.1%.
Health is P353.8 billion of the proposal, or 4.91%, and includes the DOH, the specialty hospitals and PhilHealth. For what the Universal Health Care Act promises, see part 1 of the UHC Series. For where its money is supposed to come from, see part 3 of the UHC Series.
Appropriated is not spent
DBM’s statement as of June 30, 2026, shown to Congress in August:
| Amount | |
|---|---|
| Available appropriations | P7,542.46B |
| Allotments released | P6,632.55B |
| Obligated | P3,286.15B (49.5% of allotments) |
| Disbursed | P2,692.53B (81.9% of obligations) |
An allotment is permission to commit. An obligation is the commitment itself, such as a signed contract. A disbursement is the cash leaving. A budget item can be fully appropriated and still be months from a payment. Another P909.91 billion of appropriations had not been released at all. For national government agencies alone, DBM’s own figures show P1,812.77 billion obligated against P4,265.71 billion released, an obligation rate of 42.5%. (DBCC briefing to Congress, slide 7.)
Constraints
- Congress cannot add to the President’s total. It can cut and realign, as long as the total does not rise.
- Appropriations are valid for a limited time. After that, unused money reverts unless Congress acts.
- The executive’s own release rules (allotments, SAROs, cash allocations) mean an appropriation is not a guarantee of spending.
What I’m unsure about
- I could not find who sits on the Executive Review Board. DBM’s own documents, and the Supreme Court’s description of the budget process, mention its hearings without naming its members.
- I did not research the accountability phase beyond the Constitution, the reporting deadlines in NBC 599 and the performance reviews it names.
- I did not look at re-enacted budgets before 2001. Where two sources give different lengths for the same re-enacted year, the table shows both, and I could not settle which is right.
- I have not audited any agency. The numbers are as published by DBM, the Supreme Court and the news reports linked below.
What I’d like readers to do
Correct a number, point me to DBM or COA data I missed, or tell me where the process differs in practice from what is on paper. Parts 2 to 4 take up how the NEP is generated, how the budget is managed, and how the rules have been tested.
Why this series
The problem solving series is about trying to chip at the problems of the Philippines. It is about finding solutions that may work because we will never admit defeat.
Sources
- 1987 Constitution, Art. VI Sec. 15, 24 to 27, 29; Art. VII Sec. 22; Art. IX-D Sec. 2
- Republic Act No. 12314 (2026 GAA), Sections 3, 77, 83 to 87
- DBM National Budget Memoranda: No. 156, No. 157, No. 158, and National Budget Circular No. 599
- FY 2027 National Expenditure Program, DBCC briefing to Congress (August 17, 2026)
- Supreme Court decision, G.R. Nos. 271059, 271347, E-02472 and E-04036 (October 7, 2026) and the Court’s press release (October 20, 2026)
- Re-enacted budgets: DBM, “Reenacted Budget” briefing (2019); Florencio B. Abad, “On the cusp of budget transformation”, Philippine Review of Economics 51(1), June 2014, Table 1; DBM Circular Letters 2010-1 and 2010-2; DBM status of allotment releases, December 2019; Rappler on the April 15, 2019 signing; Rappler, January 2, 2026
- Manila Bulletin: Palace to submit P7.2-T 2027 budget on Aug 11 and House gets record P7.2-T budget
The Budget Series
Problem Solving the Philippines: The Budget Series.
- Part 1: Who does what in the national budget, and where the money goes (this post)
- Part 2: How the National Expenditure Program is generated
- Part 3: How the national budget is managed (scheduled for October 30)
- Part 4: How the rules of the budget have been tested (coming soon)
Lovingly made with Claude.
Comments
17 Responses to “Problem Solving the Philippines: A Primer on the National Budget”Trackbacks
Check out what others are saying...-
[…] Problem Solving the Philippines: A Primer on the National Budget Categoriespersonal AnGoL […]
-
[…] Part 1: Who does what in the national budget, and where the money goes […]
-
[…] Part 1: Who does what in the national budget, and where the money goes […]
-
[…] Part 1: Who does what in the national budget, and where the money goes […]


Gian, thanks for this great primer about something I barely understood.
Reenactment makes me think of the Moriones festival, only Senator Sotto looks like he could fit that role while Sen. Padilla would look ridiculous.
SARO only stuck in my memory long before because that is the word for “one” in Bikol, like “sarong banggi” the song.
national budget docus and tracking tools are supposed to be accessible via cloud platforms and govt portals. interested parties as well as lgus can now track the national budget anytime, they have the code and authority for easy access.
yes. AI has allowed a chance for Good Governance and thus Good Government
Will read later today to give it the attention it deserves. Related, an interesting look at Philippine national financial standing through the Japanese credit agency.
https://www.philstar.com/business/2026/10/24/2565251/japan-credit-watchdog-sees-steady-philippines-infrastructure-investments
Retired Fil-Am doctor in the Philippines made this comment the other day:
“the nation’s supreme court declared the national budgets of ’24 and ’25 as UNCONSTITUTIONAL. the administration is appealing this decision. l stopped listening to local news. per the grapevine – the budget for ’27 is even higher. l understand, it contains essentially the same items.”
Thought it might be related to the topic.
Gemini: “No, the proposed 2027 Philippine national budget does not have the same high level of unspecified or unprogrammed funds as earlier years; instead, unprogrammed appropriations have dropped to a historic low.”
I think the Marcos government has course-corrected. Still, the President did sign the “unconstitutional” budgets.
I fear this means they have effectively converted the initially unprogrammed funds to continuing projects. This is something someone should look at. I have this Claude session to show UA movement graphically.
https://claude.ai/share/90c8a573-c8f0-494b-90db-8c7faad2248e
What we need to understand is. what happened to the projects that were not funded because programs were defunded to increase the UA funds.
you suggested po that someone should look at unprogrammed funds for continuing projects, I think po, senator pangilianan may have already got your drift. the good senator mentioned names, mainly that of the DA sec, calling for the aforementioned sec to act with prudence.
https://politiko.com.ph/farm-to-market-o-farm-to-ocean-kiko-pangilinan-questions-p108-m-road-projects-mapped-at-sea/
as saka, I am starting to think tuloy that maybe president marcos is running short of good people to appoint to top govt positions, trusted people who have the interest of our nation at their core. there may be plenty good people out there, but not popular, hence they will not be believed and will have harder time convincing underlings to do what is expected of them, rather than doing what has been priorly done to preserve the status quo.
AI AI AI AI
Yes indeed.
Possibly more unconstitutional behavior.
I dont know how useful the link below is, but I think, what the heck! numbering the projects and their corresponding coordinates would make them easier to track from start to finish, as suggested by senate pres. data to be incorporated in the new and improved govt portal.
lacson previously said there were projects with coordinates that didnt match, apparently some coordinates were in benham rise! someone apparently got away with fake coordinates as there were no prior checks and balances, or checks and balances were done with lassitude.
https://www.abs-cbn.com/news/nation/2026/10/25/gatchalian-vows-to-improve-senate-budget-transparency-portal-1655
there are grey areas of govt spending that many of us probly may or may not know.
AI Overview
Under Philippine law, certain government funds that have already been spent cannot be recalled or recovered due to the doctrine of operative fact.
The Doctrine of Operative Fact
Protection of Innocent Parties: Recognized in jurisprudence (such as Araullo v. Aquino III and applied in subsequent Supreme Court budget rulings), this doctrine dictates that actions taken or projects completed under a law or budget later declared unconstitutional may still be respected.
Completed Legitimate Projects: If funds were spent on genuine, finished projects—such as constructed public roads, school buildings, or hospital medicines—the public already received the benefit. The law does not require innocent citizens or beneficiaries to return these benefits.
Reliance in Good Faith: Individuals and ordinary entities who relied in good faith on an officially approved budget are protected from having to return the value of what was properly delivered.
Limits: When Good Faith Fails to Protect Funds
Good faith is not a blanket shield for all government spending:
Fraud and Overpricing: The doctrine of operative fact does not protect fake, ghost, or heavily overpriced projects (such as incomplete flood-control works).
Violation of Clear Rules: Under cases like Fernandez v. Commission on Audit and Social Security System v. Commission on Audit (G.R. No. 259862), public officials and recipients cannot claim good faith if they knowingly or negligently violated express legal prohibitions, budget rules, or audit mandates.
Failure to Liquidate: Under rules like COA-DBM Joint Circular No. 2015-01, a failure to properly liquidate funds (such as confidential or discretionary funds) creates a legal presumption of personal use, blocking a valid defense of good faith